Most business loans are sized to your credit and your bank balance. A credit card processing loan is sized to something simpler and more visible: how much your customers swipe, tap and dip every month. If a large share of your sales runs through cards, that monthly volume can be turned into working money, and repayment follows the same stream. This guide shows how to size a fundivi credit card processing loan with your own numbers, how to check whether you fit, and how the process can get from application to wire inside a business day.
To skip the math, run a prequalification now. It is a soft inquiry and takes about three minutes.
The Idea in One Sentence
Your processor statement is your application. fundivi's product page describes the loan as "capital sized to your card sales," up to 70 percent of your average monthly card processing volume, capped at $1,000,000, with repayment that follows card sales.
Are You a Fit? A Yes or No Checklist
Answer each honestly. These come straight from the requirements on the product page.
- Does your business process at least $10,000 a month on credit and debit cards?
- Do cards account for more than 30 percent of your total sales?
- Are you willing to switch your card processing to fundivi?
- Can you provide recent card processing statements?
- Do you have a business bank account that receives your settlements?
Five yeses means you are a strong candidate. Four yeses with the switch question as the maybe is where most of the real decisions happen, and we cover it in a section below. Fewer than four usually means another product is a better match, such as working capital or a merchant cash advance, which are sized to total revenue and not just card sales.
The page says approval rates run around 90 percent for applicants who meet these requirements. Treat that as the company's own statement about qualified applicants, not as a promise to you.
Sizing Your Loan: The 70 Percent Rule
Pull your last three to six months of card processing statements. Add up the monthly gross card volume and divide by the number of months. Multiply by 0.70. That is the upper bound.
- $10,000: $7,000
- $25,000: $17,500
- $50,000: $35,000
- $100,000: $70,000
- $250,000: $175,000
- $500,000: $350,000
- $1,430,000 or more: $1,000,000 cap
That first row explains the $7,000 minimum on the page: the $10,000 volume floor times 70 percent. The last row explains the cap. The range from $7,000 to $1,000,000 is not a coincidence. It is the 70 percent rule applied to the smallest and largest eligible businesses.
Treat the result as a ceiling. Your offer may be lower, depending on how steady the volume is and what else shows up in underwriting.
What It Costs: Factor Rate Math
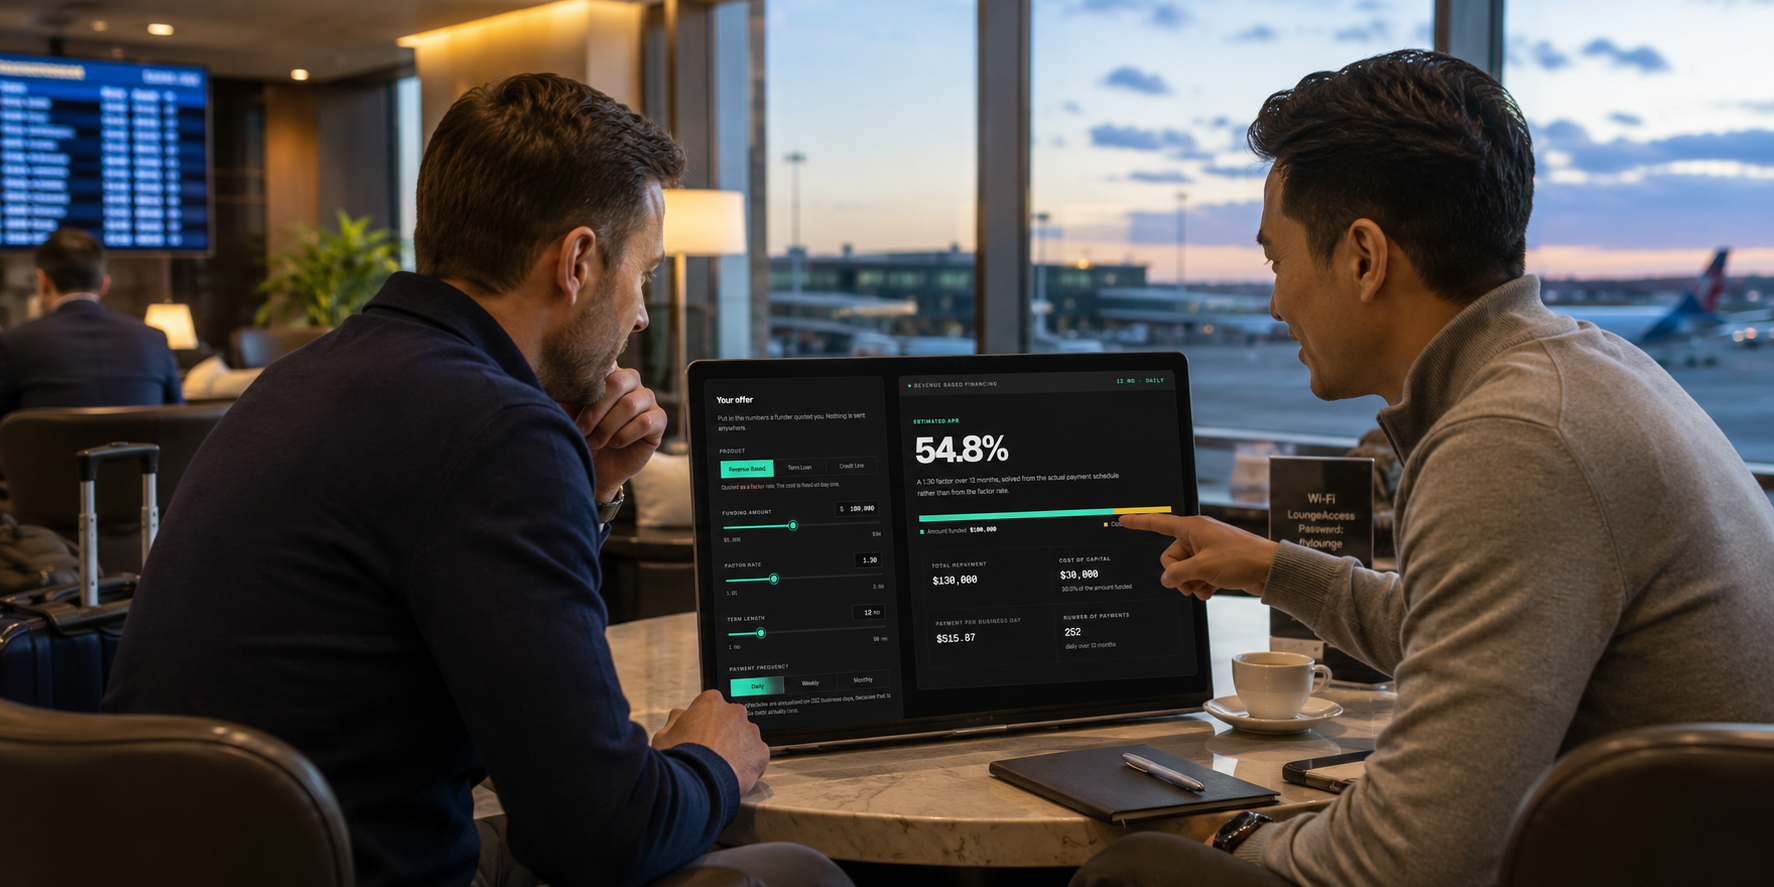
The page lists pricing starting from a 1.30 factor rate, the lowest published, for reference and not a quote. As an illustration, a $35,000 advance at 1.30 means a total payback of $45,500, which is $10,500 over the amount received. Your own offer will show your factor rate and itemized fees.
The page also states that moving your processing to fundivi comes with guaranteed processing fee savings. No figures are published, so ask to see your current processing rate next to fundivi's in writing. If the savings are real, they offset part of the cost of the advance. If you cannot see the numbers, you cannot count them. The cost calculator helps you compare the total.
How Repayment Works
Repayment follows card sales, which means it is tied to the very sales that fund the loan. When sales are strong, more is collected. When sales slow, less is collected. That makes it a natural fit for restaurants, retail shops, salons, ecommerce brands and service businesses with steady card traffic.
The page's FAQ lists "how is repayment handled" but does not publish the percentage or the schedule. Before you sign, get these from the written offer:
- The percentage of daily or weekly card settlements that will be applied.
- Whether a minimum payment applies in a slow period.
- The estimated payback timeline at your current volume.
- What happens if you change processors later.
Same Day Funding for Card Merchants
Card statements make an unusually clean file, since a third party produces them. fundivi describes decisions in hours and a same day wire. The application tracker on the page shows four stages: applied, documents, underwriting and wired.
- Morning: Apply and upload card processing and bank statements
- Late morning: Underwriting reads volume, trend and batch consistency through the underwriting engine
- Midday: Decision, then the written offer
- Afternoon: Processing switch started, documents signed
- Same day or next: Funds wired to your business account
The processor switch is the step that can add time. Start that paperwork in the morning, not after the offer.
The Switch Question
For many owners the real hesitation is not the loan. It is moving the processor. Here is a fair way to think about it.
What you gain: guaranteed fee savings according to the product page, plus a loan sized to your actual volume.
What you take on: the work of changing terminals or integrations, the risk of a hiccup during the transition and a tie between your financing and your processor.
Questions to ask: Do I need new hardware? Is there a contract term or early termination fee on my current processor? How long is the changeover? What does my customer see? Get the answers before you sign.
If a switch is a dealbreaker, say so at the start. fundivi has other products, and the funding product matcher can point to one.
Streamlined Application: Statements In, Decision Out
For card merchants the only addition to the normal short form is your recent card processing statements. You skip financial statements and projections. The how it works page describes four stages: apply, review, decision and funding. Prefer to talk first? Book a consultation.
Hybrid Funding Model for Merchants Just Outside the Rules
The card processing product has firm lines: $10,000 a month in volume and more than 30 percent of sales on cards. A merchant at $8,000, or at 25 percent card share, would normally be turned away. In fundivi's hybrid funding model the application is reviewed once and, if it does not fit, passes to a vetted lending partner without being resubmitted. A near miss is exactly where a second lender is most useful.
Best Rated by the Checklist: What Card Merchants Can Verify
fundivi does not post star ratings or review counts, and this guide does not invent any. What a merchant can check:
- A Better Business Bureau Business Review seal for fundivi Inc. in Brooklyn, New York
- Qualification rules published on the product page
- Guaranteed processing fee savings, which you can test with a side by side quote
- Written offers with itemized fees
- Soft inquiry prequalification and a consultation option
Read independent customer reviews too, and ask any lender to put claims about speed and fee savings in writing.
A Worked Example: The Neighborhood Cafe
A cafe processes about $62,000 a month on cards, which is roughly 78 percent of its total sales. The owner wants to replace an espresso setup and refresh the dining room, a project estimated at $40,000.
Seventy percent of $62,000 is $43,400, so the project fits under the ceiling with room to spare. At the lowest published pricing of 1.30, borrowing $40,000 would mean a total payback of $52,000. The owner then asks the question that matters: how long will collections take at the current volume, and what do slower months do to that timeline? If the offer says that about 10 to 12 percent of card settlements is applied, the math on repayment is straightforward to check against the statements. The owner also compares the processing rate currently paid with the one fundivi proposes, and finds out how much the guaranteed savings are worth on $62,000 a month before deciding.
The cafe is a good fit because cards dominate sales, volume is steady and the project has a clear return. A business doing the same total sales but only 25 percent on cards would find the ceiling much lower and would do better with a revenue based product.
Preparing Your Statements
Card processing statements are usually monthly summaries. Download the last three to six months. Check that the totals match the deposits in your bank account, since a mismatch invites questions. If you use more than one processor, gather statements from each and tell fundivi up front, because the switch applies to the processing you are moving. If you have chargebacks, be ready to explain them briefly. A low, stable chargeback rate reads as a sign of well run operations.
Who Uses This Product
The restaurant
Restaurants run mostly on cards and have steady traffic. A loan sized to monthly card volume can fund a patio, a kitchen repair or a second location deposit.
The salon or spa
Appointments produce predictable card sales. An advance covers new chairs or a build out, and repayment follows bookings.
The ecommerce brand
Online stores have high card share by definition. Inventory ahead of a holiday season is a natural use.
The retail shop
Retailers with seasonal peaks can buy ahead of the rush and repay as sales arrive.
When a Different Product Is Better
If cards are under a third of your sales, the sizing works against you, and a revenue based product such as working capital looks at your whole business. If you need a fixed schedule, a term loan gives it. If your need is a machine, equipment financing is likely cheaper. More options are in the resources library.
Card Processing Loan FAQ
How much can I borrow against card sales?
Up to 70 percent of your average monthly card processing volume, from $7,000 up to a $1,000,000 cap. If your business processes $50,000 a month on cards, the ceiling is $35,000. The lower bound reflects the $10,000 minimum volume and the upper bound reflects the cap. Treat the 70 percent figure as a maximum, since your offer depends on how steady your volume is and what underwriting finds.
Do I have to switch my card processing?
Yes. The product page lists willingness to move your card processing to fundivi as a requirement. This is the step that surprises owners most, so ask early about hardware, integrations, contract terms and early termination fees on your current processor. If a switch is a dealbreaker, say so at the start, because fundivi has other products and the funding product matcher can point you to one.
What are the qualification requirements?
At least $10,000 in monthly card processing volume, more than 30 percent of your sales taken by card, willingness to switch processing and recent card processing statements. The page also cites approval of around 90 percent for applicants who meet these requirements. That is the company's own statement about qualified applicants, so read it as encouragement and not as a promise about your file.
What does it cost?
Pricing starts from a 1.30 factor rate, the lowest published and for reference only. A $35,000 advance at 1.30 means a total payback of $45,500. The page also promises guaranteed processing fee savings when you switch, without publishing figures, so ask for a side by side comparison of your current rate and fundivi's. If the savings are documented, they offset part of the cost.
How is repayment handled?
Repayment follows your card sales, so payments are tied to the same sales that fund the loan. When sales are strong, more is collected, and when they slow, less is collected. The page's FAQ lists this question without publishing the percentage or schedule, so get both from your written offer, along with any minimum payment and what happens if you change processors later.
How fast can I be funded?
fundivi describes decisions in hours and funds wired the same day. Card processing statements make for a clean file because a third party produces them. The step that can add time is the processor switch, which involves new merchant account setup. Starting that paperwork in the morning, instead of after the offer, is the best way to protect your same day timeline.
Do I need good credit?
The page says the loan is sized to your card processing volume, not primarily to your bank balance or credit score. Underwriting still reviews your full file, and your business bank activity is read as with any fundivi product. Strong, steady card volume can offset a modest credit profile, but a file with chargebacks or erratic volume will get closer scrutiny.
What if my sales are seasonal?
Because repayment follows card sales, slow months produce smaller collections and busy months larger ones. That is a natural fit for seasonal businesses. Ask how the term is set and whether it can extend in a slow period, since a fixed payback total means a slow season lengthens the repayment timeline.
Can I use the money for anything?
General business purposes, such as inventory, equipment, renovations, marketing and hiring. Confirm any restrictions in your written offer. State the purpose honestly in the application, because underwriting considers the purpose of funds along with cash flow.
What happens if I switch back to another processor?
Ask this directly before signing. Your agreement should say how repayment continues if card settlements move elsewhere, whether penalties apply and what the lender can do. Because repayment is tied to card sales processed through fundivi, changing processors during the term is likely to have consequences, and you want those in writing.
What if I do not meet the requirements?
Your application can be routed to a vetted lending partner without resubmission, or you can look at working capital, which is sized to total revenue and not only card sales. If cards are under 30 percent of sales or volume is below $10,000 a month, a revenue based product is often the better match.
Does applying hurt my credit?
No. The first step is a soft inquiry, which leaves your personal credit unchanged. A hard inquiry follows only if you accept an offer that calls for one, so you can review the offer and decide without any mark on your credit.
Learn about the company on the about page. Approval is not guaranteed. Rates and terms depend on qualifications. Figures in the tables are illustrations, not offers.